In cross-border acquisitions involving Thai companies, buyers often focus on future regulatory compliance while overlooking a more dangerous threat: historical non-compliance. A target company may appear fully compliant at the time of acquisition, possess a clean corporate structure, and maintain apparently legitimate Thai majority ownership. Yet if that ownership structure was historically supported by illegal nominee arrangements, the buyer may inherit a regulatory risk capable of undermining the entire investment.
As regulatory scrutiny of foreign ownership structures continues to intensify, nominee shareholder risk has become one of the most important legal and commercial issues in Thai M&A transactions. For many sophisticated acquirers, the question is no longer whether the target company is compliant today, but whether its ownership structure has been compliant throughout its corporate history.
Under Thailand's Foreign Business Act (FBA), foreign investors are restricted from engaging in certain business activities unless an exemption, promotion, licence, or other legal basis is available. To circumvent these restrictions, some businesses historically relied upon Thai shareholders who held shares on behalf of foreign investors without genuine economic ownership or decision-making authority. Such arrangements may constitute prohibited nominee structures under Thai law.
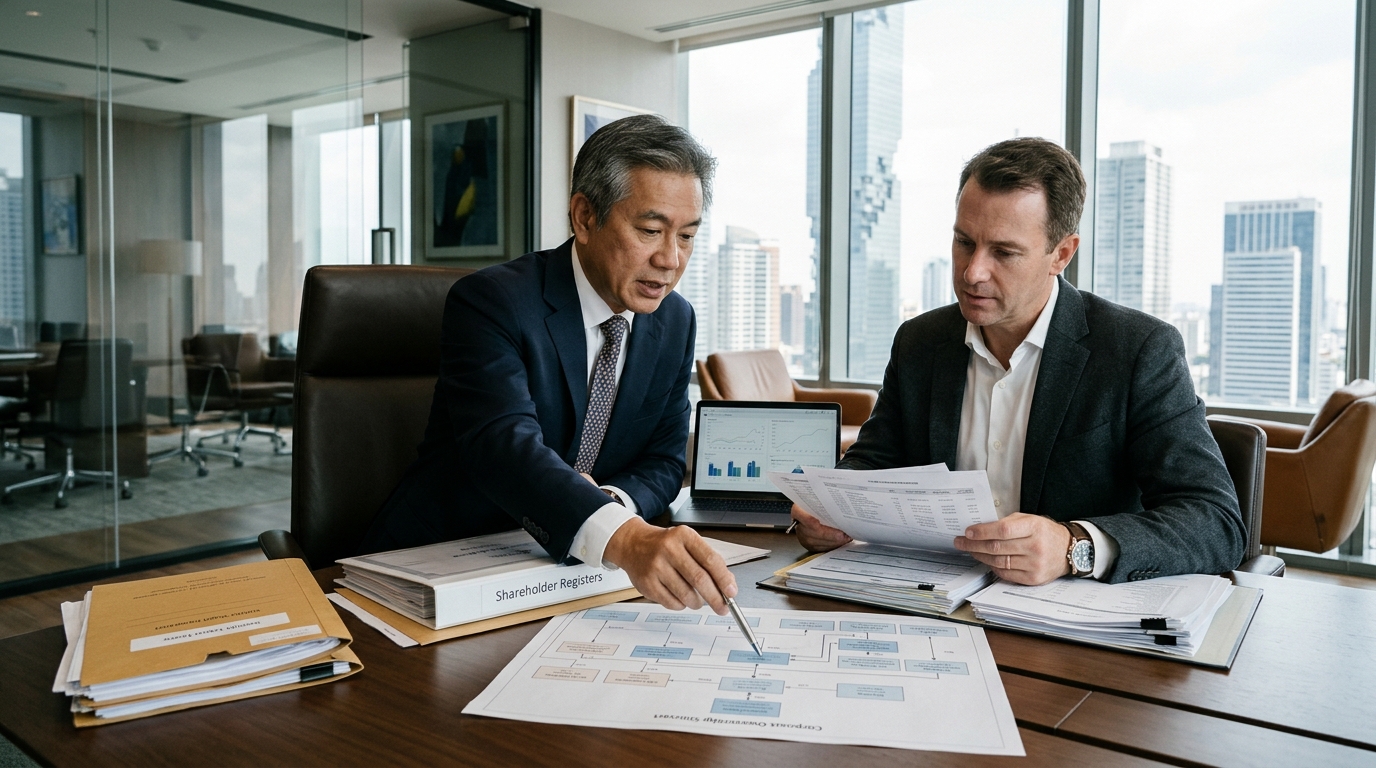
The challenge for modern acquirers is that nominee risk is often hidden beneath an apparently legitimate shareholding structure. Corporate records may show majority Thai ownership, directors may appear properly appointed, and statutory filings may reveal no obvious irregularities. However, the legal analysis does not end with a review of the shareholder register. Regulators increasingly examine the underlying substance of ownership, including the source of funds used to acquire shares, dividend entitlement arrangements, voting rights, shareholder financing structures, beneficial ownership patterns, and evidence demonstrating whether Thai shareholders exercised genuine independent control over their investments.
As a result, foreign ownership due diligence has evolved significantly beyond traditional corporate secretarial reviews. Buyers now conduct extensive investigations into shareholder funding sources, historical share transfers, financing arrangements, shareholder relationships, beneficial ownership documentation, and decision-making practices throughout the life of the target company. The objective is to determine whether the ownership structure reflects genuine investment participation or merely serves as a mechanism to circumvent foreign ownership restrictions.
The importance of this analysis extends far beyond legal compliance. Historical nominee arrangements can create substantial uncertainty regarding the long-term stability of the target company's operations, licences, regulatory approvals, contractual relationships, and ability to continue conducting restricted business activities. Even where the buyer implements a fully compliant structure following completion, questions regarding historical ownership arrangements may continue to attract regulatory attention.
This creates a unique challenge within M&A transactions. Unlike many liabilities that can be quantified through financial due diligence, historical nominee risk often remains contingent and difficult to measure. There may be no pending investigation, no regulatory notice, and no identifiable monetary exposure at the time of signing. Nevertheless, the consequences of a future investigation may be significant enough to materially affect the value of the investment.
For this reason, modern transaction structures increasingly rely upon escrow holdback mechanisms to allocate regulatory risk between buyers and sellers. Rather than paying the entire purchase price at completion, buyers may require a portion of the consideration to be retained in an independent escrow account for an extended period following closing. Depending on the level of perceived risk, holdback periods may extend for twelve, eighteen, or even twenty-four months after completion.
The commercial rationale is straightforward. If historical ownership issues emerge after closing, the buyer retains access to a dedicated recovery fund without the uncertainty and expense associated with pursuing claims directly against former shareholders. Escrow arrangements therefore function as both a risk allocation mechanism and a practical enforcement tool for indemnity obligations.
The effectiveness of an escrow structure depends heavily on the quality of the underlying transaction documentation. Sophisticated Share Purchase Agreements (SPAs) typically contain extensive representations and warranties addressing foreign ownership compliance, beneficial ownership arrangements, shareholder funding sources, historical share transfers, nominee relationships, and compliance with the Foreign Business Act. General corporate warranties are rarely considered sufficient where nominee risk represents a material concern.
In many transactions, buyers also negotiate specific indemnities covering losses arising from historical FBA violations, regulatory investigations, ownership challenges, or compliance failures predating completion. These protections are particularly important because nominee-related issues often surface only after integration activities begin and regulators undertake more detailed examinations of the company's ownership structure.
An increasingly important aspect of regulatory scrutiny involves source-of-funds verification. Authorities may examine how Thai shareholders originally financed their investments, whether funding originated from foreign investors, and whether economic ownership genuinely rests with the registered shareholders. As a result, historical banking records, shareholder loan documentation, capital contribution evidence, and investment records have become critical components of foreign ownership due diligence.
From a valuation perspective, nominee risk can have a direct impact on transaction economics. A business that appears highly valuable based on its revenues, customer relationships, licences, and market position may carry a significant regulatory discount if its historical ownership structure cannot be fully substantiated. Investors increasingly recognise that the value of a company depends not only on the assets it owns, but also on the legal certainty supporting its right to own and operate those assets.
Consequently, nominee compliance has evolved from a niche legal issue into a central M&A concern affecting valuation, deal structure, purchase price negotiations, indemnity protections, and post-closing risk management. Buyers who fail to investigate historical ownership arrangements may discover that they have acquired not only a business but also years of hidden regulatory exposure.
In today's regulatory environment, successful acquisitions require more than confirming who appears on the shareholder register. They require a comprehensive understanding of who truly funded, controlled, and benefited from the ownership structure throughout the life of the company. Where that analysis is overlooked, historical nominee arrangements can transform what appears to be a straightforward acquisition into a complex regulatory challenge long after the transaction has closed.
For sophisticated investors, escrow holdbacks are therefore not merely payment mechanisms. They represent an essential safeguard against one of the most difficult risks to identify during due diligence: the possibility that the target company's greatest liability lies not in its balance sheet, but in its corporate history.
