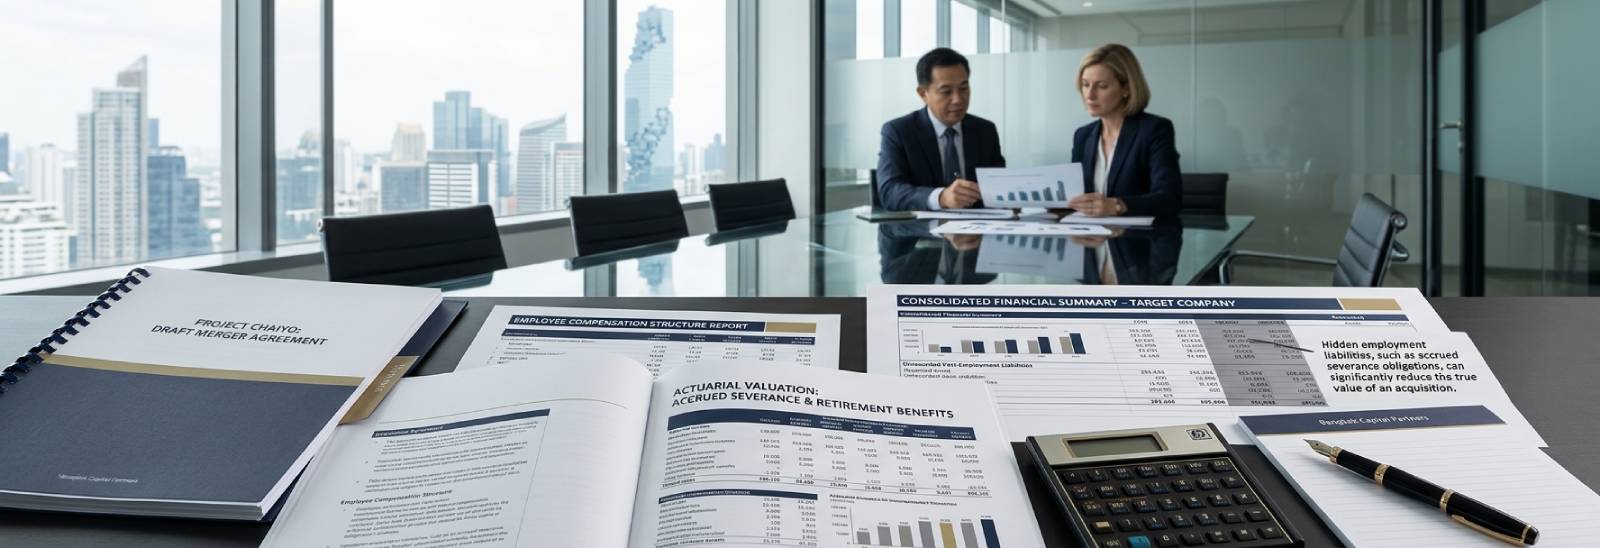
When acquiring a Thai company, buyers are not merely purchasing assets, contracts, and revenue streams—they are also inheriting years of accumulated employment obligations. Among the most frequently overlooked liabilities in Thai M&A transactions are accrued severance entitlements under Section 118 of the Labor Protection Act (LPA), which can materially impact enterprise value, post-closing cash flows, and the overall economics of a transaction.
Unlike tax assessments, litigation claims, or outstanding borrowings, severance liabilities often remain hidden beneath the surface of a target company's financial statements. While these obligations may not become immediately payable upon completion of a share acquisition, they represent a genuine economic liability earned by employees through years of service prior to closing. Consequently, sophisticated acquirers increasingly treat severance exposure as a debt-like item that should be identified, quantified, and allocated during the transaction process.
Under Section 118 of the Labor Protection Act, employees terminated without statutory cause are entitled to severance compensation based on their continuous period of employment. Depending on length of service, statutory severance may range from 30 days to 400 days of wages, with employees completing twenty years or more of service entitled to the maximum statutory benefit. Although a share acquisition does not itself constitute termination of employment, the liability remains embedded within the target company and transfers to the buyer upon completion.
This distinction is critical. In a share acquisition, the legal employer remains unchanged despite the change in ownership. As a result, employees retain their accumulated years of service and all associated statutory rights. The buyer effectively acquires the target company together with the employment history that generated these future obligations. While no severance payment arises at closing, the financial exposure remains intact and may crystallize at any time following completion.
The risk becomes particularly significant where the buyer intends to implement post-acquisition integration measures. Corporate acquisitions frequently involve the consolidation of management functions, restructuring of finance and administrative departments, elimination of duplicate roles, automation initiatives, relocation of operations, or broader organizational rationalization. Any subsequent workforce reduction may immediately trigger severance obligations that were largely accrued during the seller's period of ownership. In such circumstances, the buyer may find itself funding substantial termination costs shortly after closing despite the underlying liability having accumulated over many years before the acquisition.
From a financial due diligence perspective, buyers should not focus solely on statutory severance calculations. Equally important is assessing whether the target company has properly recognized employee benefit obligations under Thai Financial Reporting Standards (TFRS). Long-term employee benefits, including severance obligations, are generally required to be recognized through actuarial valuation methodologies. However, due diligence frequently reveals situations where provisions are incomplete, outdated, based on inaccurate employee data, or entirely absent. The key transaction issue is therefore not merely whether a provision exists, but whether the recorded liability accurately reflects the company's true exposure.
A material discrepancy between the actuarial liability and the provision recorded in the financial statements may indicate that enterprise value has been overstated. Buyers should therefore conduct a detailed review of employee demographics, salary structures, historical turnover patterns, retirement profiles, employment agreements, and actuarial assumptions used by management. Particular attention should be given to long-serving employees and senior executives whose accrued entitlements may represent a disproportionate share of the overall exposure.
The valuation implications of severance liabilities are frequently underestimated. In sophisticated transactions, accrued employee benefit obligations are often analyzed in the same manner as other debt-like items because they represent unavoidable future cash outflows arising from pre-closing activities. Employees earn severance entitlements through years of service rendered before completion; therefore, many buyers argue that the economic burden properly belongs to the seller rather than the purchaser. Where the liability is material, buyers commonly seek a corresponding reduction in the purchase price to ensure that the acquisition reflects the true economic value of the target business.
The allocation of this risk is ultimately negotiated through the Share Purchase Agreement (SPA). Depending on the findings of due diligence, buyers may require a specific indemnity for pre-completion employment liabilities, a dedicated escrow account funded by the seller, or a purchase price adjustment mechanism linked to the actuarial value of accrued employee benefits. In transactions involving anticipated restructuring initiatives, parties may also negotiate bespoke provisions addressing severance costs arising from post-closing workforce rationalization where the underlying employment service was rendered before completion.
Buyers should also recognize that statutory severance may represent only one component of potential employment-related exposure. Depending on the circumstances, liabilities may extend to payment in lieu of notice, unpaid employment benefits, retirement obligations, contractual termination payments, collective employment arrangements, and claims for unfair dismissal. These additional exposures can significantly increase the financial consequences of post-acquisition restructuring and should form part of a comprehensive employment due diligence exercise.
The analysis differs where a transaction is structured as an asset acquisition rather than a share acquisition. Asset deals may trigger separate employee transfer considerations under Thai labor law, requiring careful assessment of employee consent requirements and the preservation of existing employment rights. Accordingly, transaction structure can materially influence both legal risk and financial exposure, making employment considerations an important factor in determining the optimal acquisition strategy.
Ultimately, Section 118 severance obligations should not be viewed merely as an HR compliance issue. They represent a potentially significant contingent financial liability capable of affecting valuation, deal structure, purchase price negotiations, and post-closing integration costs. In today's Thai M&A market, experienced buyers increasingly treat accrued severance exposure as a core financial due diligence item rather than a routine employment law review.
The most successful acquirers understand a simple but important principle: employees earn severance benefits long before they are paid. If those obligations are not properly identified and reflected in the transaction economics, the buyer may inherit a substantial financial burden that erodes anticipated investment returns. Proper due diligence, accurate actuarial analysis, and carefully drafted SPA protections remain essential tools for ensuring that employment liabilities are allocated fairly between buyer and seller and that no hidden workforce costs emerge after completion.
