As Thailand continues to strengthen its tax administration and enhance scrutiny over cross-border financial transactions, many foreign residents and high-net-worth individuals have explored using family gifts or private loans as a means of transferring funds into Thailand. However, a critical misconception persists: simply describing a remittance as a "gift" or "loan" does not automatically determine its tax treatment.
The Thai Revenue Department increasingly applies a substance-over-form approach when reviewing financial arrangements. During a tax audit, officials may examine the commercial reality of a transaction rather than relying solely on the wording used in bank transfer instructions or private correspondence. If supporting evidence is insufficient or inconsistent, funds originally presented as gifts or loans may be reclassified as assessable income, potentially resulting in additional tax liabilities, surcharges, and penalties.
For international taxpayers, this means that tax planning must be supported by credible legal documentation and a demonstrable factual background rather than relying on terminology alone.
Understanding Section 42 Exemptions Is Only the Starting Point
Thailand's Revenue Code provides specific exemptions for certain gifts, reflecting the distinction between genuine family wealth transfers and taxable income. Under the current framework, maintenance payments or gifts received from ascendants, descendants, or spouses may qualify for exemption up to THB 20 million per tax year, while qualifying gifts from persons outside those categories are generally exempt only up to THB 10 million per tax year, provided the statutory conditions are satisfied.
These exemptions, however, should not be interpreted as automatic safe harbors. Revenue authorities may request evidence demonstrating the identity of the donor, the family relationship, the donor's financial capacity, the purpose of the transfer, and whether the transaction genuinely represents a gratuitous transfer rather than disguised compensation, business revenue, investment proceeds, or other taxable receipts.
In practice, the legal characterization of a transaction depends not only on the statutory exemption but also on whether contemporaneous evidence consistently supports the taxpayer's position.
Loans Require Genuine Commercial Characteristics
Private loans between family members or related parties present another area of increasing regulatory attention. A transaction described as a loan should exhibit characteristics that are ordinarily expected in a bona fide financing arrangement.
Professional tax advisers generally recommend executing written loan agreements before any funds are transferred, specifying principal amounts, repayment obligations, maturity dates, governing law, and where appropriate, interest provisions or repayment schedules. Bank records should align with contractual terms, and any subsequent repayments should be capable of independent verification.
Where funds are transferred without documentation, without repayment expectations, or where the surrounding facts contradict the stated arrangement, the Revenue Department may question whether the purported loan is in fact an undisclosed gift or taxable income. Such reclassification can significantly alter the tax consequences for the recipient.
For multinational families and expatriates, maintaining contemporaneous records is often far more important than attempting retrospective explanations during an audit.
Building an Audit-Ready Position in the Era of Enhanced Compliance
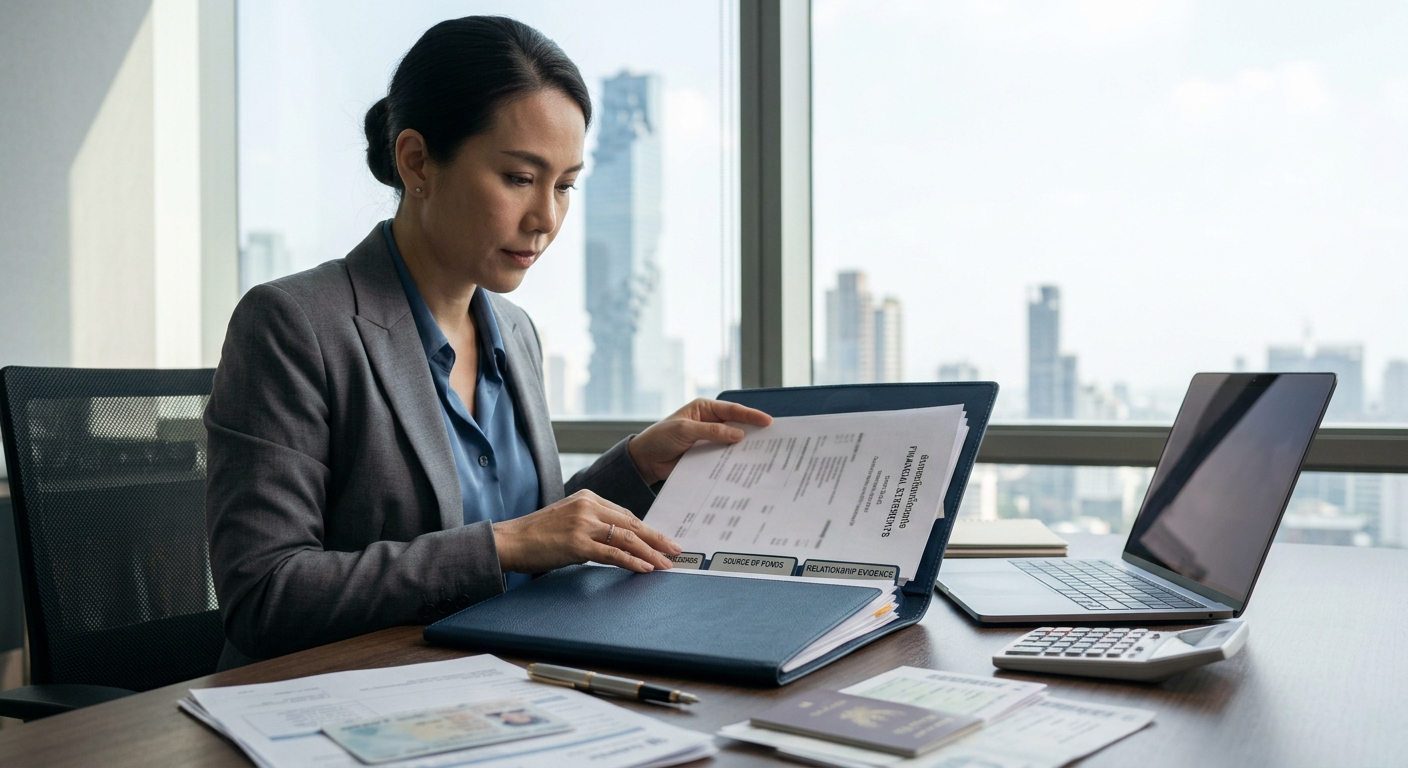
As Thailand's tax enforcement becomes increasingly data-driven, taxpayers should adopt a proactive compliance strategy rather than relying on assumptions about historical practices. Financial institutions, international information exchange mechanisms, and enhanced audit capabilities enable authorities to examine cross-border transactions with greater sophistication than in previous years.
An audit-ready file should ideally include donor declarations, evidence of family relationships, source-of-funds documentation, executed gift deeds or loan agreements, bank transfer records, and any correspondence explaining the commercial purpose of the transaction. Consistency across these documents substantially strengthens the taxpayer's position if questions arise in the future.
Ultimately, successful tax planning is not achieved by changing the label attached to a remittance but by ensuring that the legal form accurately reflects the underlying economic reality. In Thailand's evolving tax environment, documentation has become one of the most valuable forms of tax risk management, protecting taxpayers against costly reclassification disputes and reinforcing the credibility of legitimate cross-border wealth transfers.
